GKV contributions and PKV premiums are calculated in different ways, and both can change over time. A contribution rate, a contribution ceiling, a tariff adjustment and a change in household circumstances are not the same event, even when they all affect the amount someone pays.
The central principle: Historical contribution development can help explain how GKV and PKV financing has evolved, but aggregate historical percentages cannot predict the future cost of either system for an individual person.
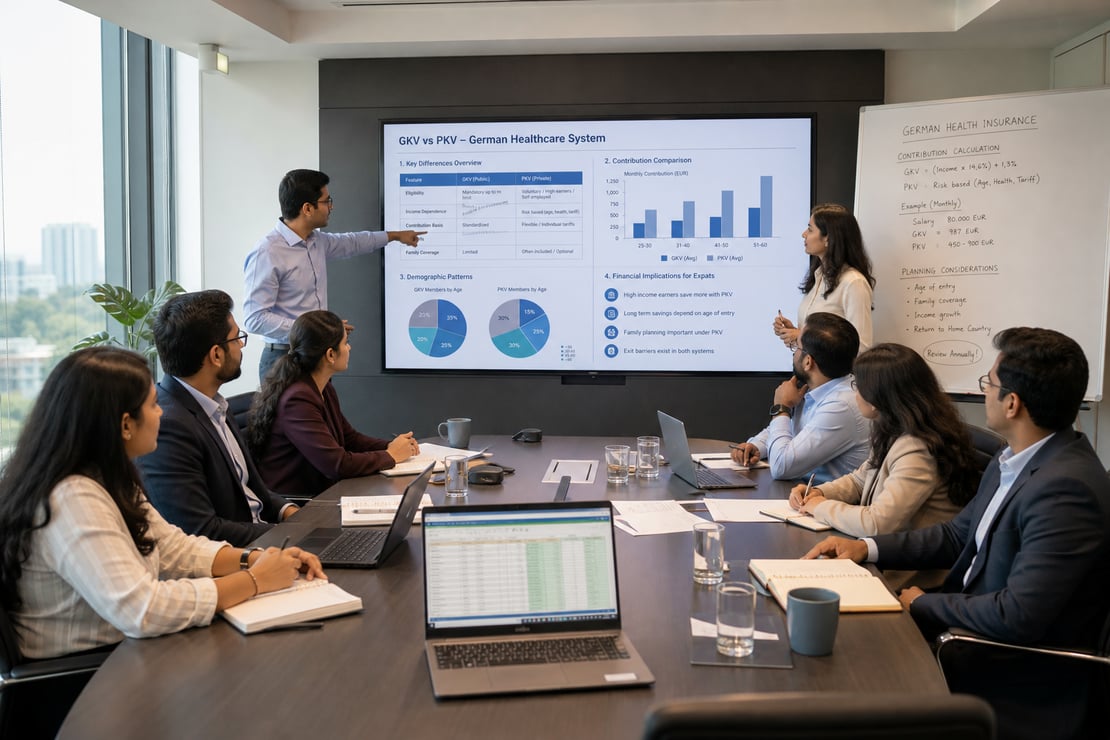
GKV Contributions and PKV Premiums Are Calculated Differently
GKV contributions are mainly income-related. The statutory contribution rate and the insurer-specific additional contribution are applied to contribution-relevant income, subject to the Beitragsbemessungsgrenze (BBG). Employment status and the type of income also affect the calculation.
PKV premiums are generally not income-based. They are calculated from the selected tariff and contractual benefits, the insured risk at entry and the person’s entry age, with the applicable actuarial and legal rules. Health underwriting can affect the terms offered when a person applies.
The Jahresarbeitsentgeltgrenze (JAEG) and the Beitragsbemessungsgrenze (BBG) have different jobs:
- JAEG: the income threshold that determines when an employee may become exempt from compulsory statutory health insurance under the applicable rules.
- BBG: the ceiling on income used to calculate statutory health and care contributions.
Crossing the JAEG does not itself determine the amount of GKV contributions. It concerns insurance status; the BBG and the applicable contribution rules determine how much income is assessed.
| Dimension | GKV | PKV |
|---|---|---|
| Basis | Contribution rate and additional contribution applied to contribution-relevant income up to the BBG. | Tariff and contract-based premium calculated using the applicable risk and actuarial rules. |
| Income effect | Income changes can change the contribution, subject to the BBG and membership status. | The premium is generally not linked directly to current income. |
| Family effect | Eligible relatives may qualify for family insurance under statutory conditions. | Separately insured family members generally require their own contracts and premiums. |
| Employer contribution | Employer and employee generally share the health contribution and the additional contribution. | The employer subsidy is capped by the statutory GKV-based calculation and the qualifying premium. |
| Health underwriting at entry | Compulsory membership is not individually priced through private health underwriting. | Health and age at entry can affect acceptance, surcharges, exclusions and the initial premium. |
| Contract benefits | Benefits follow the statutory framework and can change through legislation. | Benefits depend on the selected contract and tariff wording. |
| Adjustments | Rates, additional contributions, income and ceilings can change through different mechanisms. | Premium adjustments follow regulated actuarial, contractual and legal mechanisms. |
| Retirement | Costs depend on insurance status and the income and contribution rules that apply in retirement. | Premiums remain contract-based; an eligible pensioner may apply for a limited statutory subsidy. |
2026 reference values: The JAEG is €77,400 per year or €6,450 per month. The health and care BBG is €69,750 per year or €5,812.50 per month. The general GKV contribution rate is 14.6%.
The official average additional contribution used for 2026 calculation tables is 2.9%. BMG also reported an observed average additional contribution of 3.13% as of 1 April 2026. These figures describe different concepts: the first is the official calculation average, while the second describes the average charged by insurers at that date.
The social-care contribution is 3.6% in 2026, or 4.2% for relevant childless members after the surcharge. Saxony has a different employer and employee split.
What Drives GKV Contributions?
A GKV member’s amount can change for several separate reasons:
- The general contribution rate: the statutory rate currently used for the general case is 14.6%.
- The insurer-specific additional contribution: each fund sets its own additional contribution within the statutory framework. For employees, the employer generally shares this contribution.
- Contribution-relevant income: employment income and, for some membership categories, other income are assessed according to the applicable rules.
- The BBG: income above the ceiling is not included in the ordinary health and care contribution calculation.
- Employment or membership status: employees, voluntary members, self-employed people and pensioners can be assessed differently.
- Long-term care: the care contribution is separate from the health contribution and has its own childless surcharge and regional exception.
- Legislation: Parliament can change rates, thresholds, eligibility rules or the treatment of family-insured people.
Demographic and healthcare-cost developments may influence policy and financing decisions, but they do not create a predetermined personal contribution increase. A person’s income, insurer, membership status and household circumstances still matter.
What Drives PKV Premiums?
PKV premiums reflect the selected tariff, the contractual benefits, the insured risk at entry and the person’s entry age. A health assessment can lead to a risk surcharge, a benefit exclusion or a refusal outside the statutory Basistarif rules.
Part of a premium is used to build ageing provisions. These provisions are intended to spread expected future healthcare costs over the period of cover. They are important to the calculation, but they do not guarantee that a premium will remain fixed or affordable.
It is therefore too simple to say that a PKV premium rises because the policyholder gets older. Entry age affects the initial calculation. Later adjustments follow the applicable actuarial, contractual and legal mechanisms, which can include changes in claims expenditure and other calculation assumptions. Section 203 of the German Insurance Contract Act (VVG) governs important parts of the premium-adjustment process.
A deductible can also affect the premium and the person’s out-of-pocket costs. It should be included in a comparison rather than treated as a free saving.
Why Contribution and Premium Adjustments Happen
GKV and PKV can both become more expensive, but the route is different.
For GKV, a change may result from the general contribution rate, an insurer’s additional contribution, a change in the BBG, a change in contribution-relevant income or a legislative change. A higher BBG is not the same thing as a higher contribution rate: it can increase the amount assessed for someone whose income is above the previous ceiling.
For PKV, an adjustment may follow regulated recalculation mechanisms, claims expenditure, actuarial assumptions or tariff-specific circumstances. The adjustment is not simply a percentage applied to everyone in private insurance, because individual contracts and tariffs differ.
For 2027, enacted legislation provides an additional €300 monthly or €3,600 annual increase to the relevant JAEG and BBG adjustment mechanism, on top of the ordinary annual adjustment process. The exact final annual threshold amounts should be checked against the applicable 2027 social-insurance calculation regulation once available.
What Historical Cost Development Can — and Cannot — Tell You
Historical GKV information can show how statutory rates, additional contributions, BBG values and JAEG values have changed. Those figures are useful for explaining the financing system, but they measure different mechanisms and should not be combined into one personal cost forecast.
PKV industry data measures something different again. An industry aggregate such as contribution revenue per insured person is not the payment history of one person’s tariff. The result can be affected by the composition of the insured population, tariff changes, age structure, benefit levels and other factors.
For that reason, a headline such as “GKV increased by X% while PKV increased by Y%” is not an apples-to-apples answer to an individual’s future cost question. It does not account for income, the BBG, family insurance, employer support, benefits, deductibles or the individual PKV tariff.
Use history to understand mechanisms, not to declare a lifetime cost result. No one system is universally better; the fit depends on the person’s circumstances.
How Employer Contributions Affect the Comparison
Employer support changes an employee’s personal net cost. For ordinary 2026 employee health insurance, applying the €5,812.50 monthly BBG, the 14.6% general rate and the 2.9% official calculation average produces an employer health-subsidy ceiling of approximately €508.59 per month. The actual qualifying premium cap still applies, so this is not an unconditional payment to every employee.
The same statutory ceiling principle applies when an eligible employee is privately insured. The employer does not automatically pay half of every premium without limit; the subsidy is tied to the statutory GKV-based calculation and the qualifying premium.
For social care, the ordinary maximum employer share is approximately €104.63 per month in most federal states. In Saxony, the employer share is approximately €75.56 because the statutory employee and employer split is different. These figures are contribution ceilings, not universal payroll outcomes.
How Family Situation Changes the Cost Picture
Family circumstances can change the household comparison substantially. Under statutory family-insurance rules, eligible spouses, life partners and children may be covered through GKV without their own separate contribution, provided the relevant income, insurance-status and other conditions are met.
Separately insured family members in PKV generally require their own contracts and premiums. That does not establish which system is cheaper for every household; it means that family structure must be included in the calculation instead of comparing one adult’s premium in isolation.
From 1 January 2028, an enacted amendment introduces a 2.5-percentage-point contribution surcharge for certain members who have a spouse or life partner covered through statutory family insurance. The member bears the surcharge. It is not a separate flat premium paid by the spouse, it is not universal, and the law contains statutory exceptions, including specified situations involving children, caregiving, retirement age and disability.
What Changes in Retirement?
GKV and PKV remain different systems in retirement. GKV costs depend on the person’s insurance status and the income and contribution rules that apply to that status. PKV premiums remain contract-based.
Privately insured pensioners may, under the applicable rules, apply for a statutory pension-insurance subsidy. The subsidy is limited, may be capped by the actual premium and does not cover private long-term-care insurance. GKV pensioners can also be subject to different rules depending on whether they are compulsory or voluntary members.
Neither system is automatically cheaper for every retiree. Ageing provisions do not guarantee affordability, and a responsible comparison should model the person’s insurance history, income sources, employer or pension subsidy and household situation rather than applying a blanket retirement verdict.
Why Today’s Cheapest Option May Not Be Tomorrow’s Cheapest
A personal price comparison can change when any of its assumptions changes. Relevant factors include:
- income and contribution-relevant income;
- the BBG and the insurer’s additional contribution;
- the selected PKV tariff and premium adjustment;
- family-insurance eligibility and the number of separately insured people;
- the employer contribution;
- employment or membership status;
- retirement status and available subsidy; and
- contractual benefits, deductibles and protection gaps.
Today’s lower personal payment does not prove that the same system will remain lower over an entire career. Historical averages cannot establish that either.
How to Compare Costs Without Predicting the Future
A useful comparison separates facts from forecasts. Start with these questions:
- What do I pay today, and which part is supported by my employer?
- Which income and membership rules determine my current GKV assessment?
- What would happen to the household cost if my income, employment or family situation changed?
- Which PKV benefits, deductible and contractual assumptions are being compared?
- What is known from enacted law, and what is only a forecast or proposal?
- How would the calculation change in retirement?
- Which decision would still make sense if the historical average did not repeat?
This approach does not require predicting the future. It makes the assumptions visible and helps identify which questions need an individual review.
Where to Go Next
For a broader system comparison, read our comparison of GKV and PKV in practical terms. For the wider decision framework, see the complete PKV decision guide.
If your question is specifically about a high income before changing systems, review the questions to consider before switching to PKV. For long-term contract and affordability risks, read our guide to long-term PKV risks.
Primary references for the figures and legal rules include the Federal Ministry of Health contribution information, the Federal Government’s 2026 social-insurance thresholds, and the promulgated GKV contribution-stabilization law.
Where the answer depends on your own income, household, employment history or existing contract, you can request an individual consultation. A suitable outcome may be to stay in GKV, consider PKV, review existing PKV cover, close a specific protection gap or make no change.