Lower than average income
You receive fewer pension points.

For Indian Expats in Germany
Gesetzliche Rentenversicherung · bAV · Private retirement
Understand what pension rights you are building in Germany, what your employer may add, and which private options could help close a retirement gap, especially if your future may be in Germany, India or both.
Understand your German pension
Explore your retirement options
Plan for Germany, India or both
Where to start
If you work in Germany, you usually pay into the statutory pension (gesetzliche Rentenversicherung) every month together with your employer. That gives you real pension rights, but it does not automatically mean your retirement income is fully covered.
For Indian professionals, one factor matters especially: many start contributing to the German system later in their career or may not spend their entire working life in Germany.
The first step is therefore not choosing another pension product. It is understanding what you are already building through the statutory pension, what your employer may provide and whether there is actually a gap to fill.
This guide takes you through that picture and shows what changes when your future may involve Germany, India or both.
Is the German state pension enough for retirement? There is no universal yes or no. The answer depends on your contribution history, pension points, income history, retirement age, career interruptions, desired retirement income, other retirement provisions and where you may live in retirement.
The foundation
Germany's statutory pension (gesetzliche Rentenversicherung) largely works on a pay-as-you-go system called the Umlageverfahren.
The contributions paid by today's employees and employers are used to finance current pensions. They are not invested in an individual retirement account in your name.
Today’s workers
Employees and employers contribute to the statutory pension system through salary contributions. In 2026, the general contribution rate is 18.6% of pensionable gross income, generally shared equally between employee and employer.
Today’s retirees
Current retirees receive pensions funded by today’s contributions and other available system funding.
Your contributions do not build a personal savings account. Instead, they create pension rights called Entgeltpunkte, commonly called Rentenpunkte. These points are later used to calculate your own statutory pension.
The Umlageverfahren explains how the system is financed.
To understand your own future pension, the next step is understanding Rentenpunkte.
The calculation
You receive fewer pension points.
You receive around one pension point for that year.
You receive more pension points, up to the annual contribution ceiling.
Many Indian professionals start contributing in Germany later in their career. Fewer contribution years usually mean fewer pension points, so the statutory pension may become one part of retirement income.
Your annual statement
Once you have built up enough pension history, Deutsche Rentenversicherung sends you a yearly Renteninformation.
It shows what pension rights you have already earned and what your future statutory pension could look like based on certain assumptions.
For Indian professionals, the important point is this: the projection assumes continued contributions. If you spend fewer years working in Germany, your final pension may be very different.
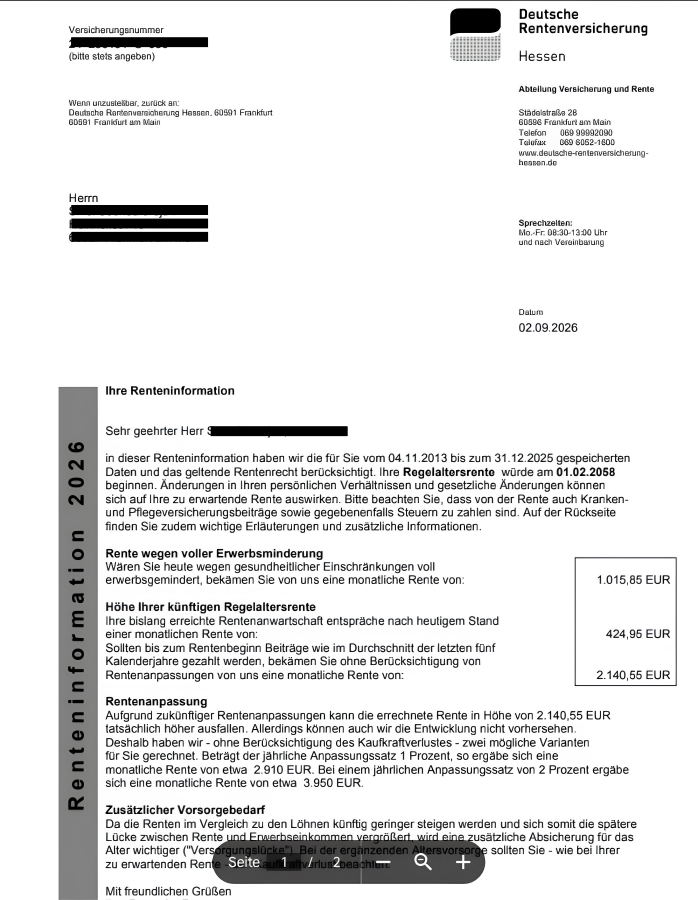
Many Indian professionals arrive in Germany after starting their careers elsewhere. The projection assumes many more years of contributions in Germany, so your current pension rights may look much smaller than your future projection.
The important question is not only how much Germany provides, but whether your total retirement income fits the life you want to build.
Your expat career
The German statutory pension grows through contribution years and earnings points (Rentenpunkte).
Someone who works in Germany from the beginning of their career can build many more pension points than someone who arrives later.
For Indian professionals, this is one of the biggest differences compared with someone who spends their entire working life in Germany.
Illustrative career patterns only. These are not customer cases or guaranteed pension outcomes.
Full career in Germany
More pension points built over a long working life.
Arriving mid-career
A smaller statutory pension because fewer points are collected.
Shorter stay in Germany
The statutory pension becomes one part of retirement planning rather than the complete picture.
The German pension system rewards contribution history.
Arriving later does not mean you receive nothing. It simply means your German statutory pension may cover only part of your future retirement income.
Try it yourself
A simple estimate of what your German statutory pension could provide and how much additional retirement income you may want to plan for.
This is not a prediction of your final pension. It is a first overview based on your age, income and expected years of contribution.
The calculation is a simplified illustration based on current assumptions. Your actual pension depends on your individual earnings history, contribution periods and future pension rules.
Contributing in Germany until 67 adds up to about 37 years of contributions in this estimate.
Estimated statutory pension
€1.583/ month
Additional retirement income to plan for
€917/ month
On these inputs the statutory pension already meets your target. You may still want to consider inflation and years spent outside Germany when planning your retirement income.
With fewer than five qualifying years (60 qualifying months), this simple estimate does not show a statutory pension yet. Your eligibility and how contributions are treated can depend on your circumstances and applicable international rules.
Your statutory pension depends mainly on:
For Indian professionals, one of the biggest factors is often not income alone, but the number of years spent contributing in Germany.
Illustrative estimate only. The calculation uses simplified assumptions and is not a personal pension forecast. Your actual statutory pension depends on your individual contribution history and future pension values.
Want to understand your own retirement picture in more detail?
Review your retirement planThe structure
Germany traditionally divides retirement planning into three layers (Schichten). The model helps explain how different retirement solutions are structured. It does not automatically mean that everyone needs all three layers.
Layer 1 · Basic provision (Basisversorgung)
Includes:
Purpose:
Long-term retirement income with a strong focus on lifelong pension payments.
Key point:
Limited flexibility, but designed specifically for retirement provision.
Layer 2 · Supported retirement provision (Geförderte Vorsorge)
Includes:
Purpose:
Retirement saving with employer support or government-supported structures.
Key point:
Understand employer contributions, costs, rules and flexibility before choosing.
Layer 3 · Private provision (Private Vorsorge)
Includes:
Purpose:
Additional wealth building with more personal flexibility.
Key point:
More flexibility can also mean fewer direct subsidies.
The Altersvorsorgedepot is a new product category under Germany’s reform of tax-supported private retirement provision. The reform was approved in 2026, and providers may offer new products from 1 January 2027.
It is designed to give savers a more capital-market-oriented option within a regulated retirement framework, but it is not a statutory pension entitlement.
Unlike a normal investment account, it follows specific rules for contributions, eligible investments, retirement use and withdrawals.
For international professionals, the important questions are:
Understanding the framework
Tax treatment is one factor when comparing retirement options in Germany. The right choice depends not only on possible tax advantages, but also on flexibility, costs, employer support and your plans for Germany or India.
| Option | During saving | During retirement | Important |
|---|---|---|---|
| Basisrente (Rürup) | Contributions may offer tax advantages within applicable rules. | Pension payments are taxed according to the rules applying at that time. | Designed for long-term retirement provision with limited flexibility. |
| Employer pension (bAV) | Depending on the arrangement, contributions and employer support may provide advantages. | Benefits are taxed according to the applicable rules. | Check employer contributions, costs and what happens when changing jobs or leaving Germany. |
| Private retirement solutions | Tax treatment depends on the type of solution. | Rules depend on the specific product. | More flexibility can come with fewer direct incentives. |
| Altersvorsorgedepot from 2027 | New product category under the reform; providers may offer products from 1 January 2027. | Rules should be checked once the framework is implemented. | For expats, flexibility and international suitability matter. |
Tax advantages are only one part of retirement planning. A solution should also fit your timeline, flexibility needs and future plans.
Two countries, one plan
Many Indian professionals build a life between two countries. You may retire in India, stay in Germany or keep options open.
Your retirement planning therefore has two questions:
What rights have I built in Germany?
How flexible are my choices if my future changes?
Moving to India does not automatically cancel German pension rights you have already built. Whether and when you have a German pension entitlement depends on the applicable requirements. The Germany–India social security agreement may be relevant when insurance periods are considered.
Payment of a German pension in India, a possible refund of contributions and tax treatment are separate questions. This guide provides general information, not individual legal or tax advice.
Working in Germany creates pension rights through the statutory pension system.
The Germany–India social security agreement is relevant to the statutory pension insurance framework. Under the applicable conditions, insurance periods from both countries may be considered when checking certain pension rights. Your Indian employment history does not simply become German pension contributions or German Rentenpunkte.
If you leave Germany after a shorter period, the question is not simply “can I get my money back?”
A contribution refund is possible only if the statutory requirements are met. Nationality, insurance status, residence and other conditions can be relevant.
A refund is not the same as receiving a pension later and can affect pension rights connected to the contributions. Check the current Deutsche Rentenversicherung rules before applying.
Private retirement solutions can offer additional flexibility, but every contract has its own rules.
Before choosing a long-term solution, check:
For current legal and calculation information, use the following primary sources from Deutsche Rentenversicherung, BMAS and the Federal Ministry of Finance:
The goal is not to choose a Germany-only or India-only plan.
It is to build retirement income that fits the life you may actually live.
Common questions
For the general qualifying period for a regular German old-age pension, you generally need five years or 60 qualifying months.
This does not mean you must work in Germany for exactly five years. Other pension types can have different requirements, and international insurance periods may be relevant under an applicable social security agreement.
Moving to India does not automatically cancel German pension rights you have already built.
Whether and when you have a German pension entitlement depends on the applicable requirements. The Germany–India social security agreement may be relevant when insurance periods are considered. Payment of a German pension in India, a possible refund of contributions and tax treatment are separate questions.
A contribution refund is possible only if the statutory requirements are met.
Nationality, insurance status, residence and other conditions can be relevant. Possible pension rights and insurance periods must be considered separately: a refund is not the same as receiving a pension later and can affect pension rights connected to the contributions.
Check the current Deutsche Rentenversicherung rules before applying.
The Altersvorsorgedepot is a new product category under Germany’s reform of tax-supported private retirement provision.
The reform was approved in 2026, and providers may offer new products from 1 January 2027. The contribution, withdrawal and eligibility rules should be checked against current official information. This future reform is not a statutory pension entitlement.
A company pension (betriebliche Altersvorsorge, bAV) can be an additional retirement layer, especially if your employer contributes.
Whether it makes sense depends on factors such as employer contribution, costs, contract conditions and how long you expect to stay in Germany.
Many Indian professionals start their German career after already building part of their working life in India. This can mean fewer years of German pension contributions and fewer Rentenpunkte compared with someone who spends their full career in Germany.
Whether the German state pension is enough depends on your contribution history, pension points, income history, retirement age, career interruptions, desired retirement income, other retirement provisions and future country of residence.
The Germany–India social security agreement is relevant to the statutory pension insurance framework. Under the applicable conditions, insurance periods from both countries may be considered when checking certain pension rights.
Your Indian employment history does not simply become German pension contributions or German Rentenpunkte, and not every period is automatically recognised. Your individual situation depends on your contribution history and circumstances.
If you qualify for a German statutory pension, it can generally be paid while living abroad, including when you live in India.
Entitlement and payment are separate questions: the pension type, personal requirements and administrative steps can matter. Tax treatment in Germany or India is a separate question and is not determined by this general rule.
The next step
Planning retirement in Germany is not about finding one perfect product. It starts with understanding what you already have, what your employer provides and what options may fit your future.
As a licensed Versicherungsmakler (insurance broker), NEOdirect helps Indian professionals compare retirement solutions, understand German pension rules and make decisions with Germany and India in mind.

Bring your Renteninformation and whatever you already have. We will help you understand what you have built, what options exist and what questions matter next.
NEOdirect · Insurance broker for expats in Germany