Imagine that an international employee in Germany receives a letter from their landlord about a dispute, or a notice that their employment is ending. They already have legal insurance. But the letter raises practical questions: Who should they contact? Do they need a lawyer? Should they call the insurer first? Which number is correct? Is this type of dispute covered, and is it worth taking further?
This is an illustrative situation, not a story about a particular NEOdirect client. It shows the difference between owning a policy and having someone help you understand what to do next. An insurance policy is a document. Having someone who helps you when things go wrong is a service. At NEOdirect, you get both.
If you want to understand what legal insurance in Germany may cover, our legal insurance page explains the service, and our complete guide covers the policy basics.
Good insurance matters. So does the service around it.
A policy can be well designed and still feel difficult to use when you are new to Germany, working in a second language, or dealing with a stressful letter. You may not know whether to contact the insurer, a lawyer, or the person who arranged the policy. You may also be unsure what information to provide or whether a waiting period applies.
A personal insurance adviser can help you look at the situation from the insurance side: what your contract says, which department to contact, what the insurer needs, and what the next practical step might be. That does not replace a lawyer or guarantee that an insurer will cover a particular matter. It means you do not have to work out the insurance process alone.
Experience changes what a useful recommendation looks like
Martin B. Grödl has spent more than 30 years working in the German insurance market. In earlier years, ARAG, KS/AUXILIA and ROLAND were among the legal-protection insurers he most often recommended to German clients. He still considers them credible providers for the right situation.
As NEOdirect began focusing more on international professionals and expats, the questions clients brought to a consultation changed. Price and deductible still matter, but so do waiting periods, understandable policy wording, access to initial legal guidance in English, and the quality of personal service.
For many international clients, NRV is now one of the providers we often assess. That is not a claim that NRV is automatically better than ROLAND or ARAG. The right answer depends on the person, the tariff and the cover they actually need. Allianz, ERGO and ADVOCARD are also among the established providers we may consider.
For example, a client who places particular importance on certain family or marriage-related legal benefits may find a specific ARAG tariff more suitable, even if it costs more. Those benefits depend on the exact tariff and can be subject to waiting periods, exclusions and limits. They should never be read as a promise that every divorce or family-law cost will be paid.
We explain the trade-offs and let clients decide what matters to them. We advise and recommend; we do not pressure someone towards one insurer.
You can see the broader range in our overview of insurance providers we work with.
We do not need to give you 15 quotes
Most people are not looking for a stack of complicated offers that they have to compare alone. They want suitable cover, a price they understand, clear conditions, a person to contact, and a sensible plan for what happens if something goes wrong.
Our work is to understand those priorities, consider a sufficiently broad and relevant selection, and explain why a recommendation fits. German insurance law sets duties around the basis of a broker’s recommendation and advice. In particular, Section 60 of the Insurance Contract Act (VVG) concerns the basis for advice, and Section 61 VVG addresses asking about needs, advising and documenting the advice. The scope of a recommendation and any limitations must be handled transparently.
A comparison platform can be useful for seeing available offers. But an insurance broker versus comparison platform is not simply a choice between “good” and “bad.” A result page does not by itself answer what to do with a policy later, whether another broker can service it, or whom to call when an insurer’s reply is unclear.
We do not believe more quotes automatically lead to better decisions. We believe better advice does.
Recommendations are informed by real servicing experience
NEOdirect continues to look after hundreds of clients whose existing policies are with different insurance companies. Some of these relationships go back years. This gives us practical experience that goes beyond reading tariff documents.
In day-to-day work, we see how insurers respond to questions, how easy it is to reach the right department, how requests are handled, and where a process can become difficult. Those are observations from real service work, not a blanket verdict on an entire company. One client’s experience does not prove how every case will be handled.
Products, prices and service processes change. A recommendation that made sense two years ago may need a fresh look today. That is why an insurance policy review in Germany should start with the client’s current contract and needs, not with an assumption that a new policy is always better.
If you would like to speak with Martin directly, you can book a meeting with him.
What DKM 2026 means for our clients
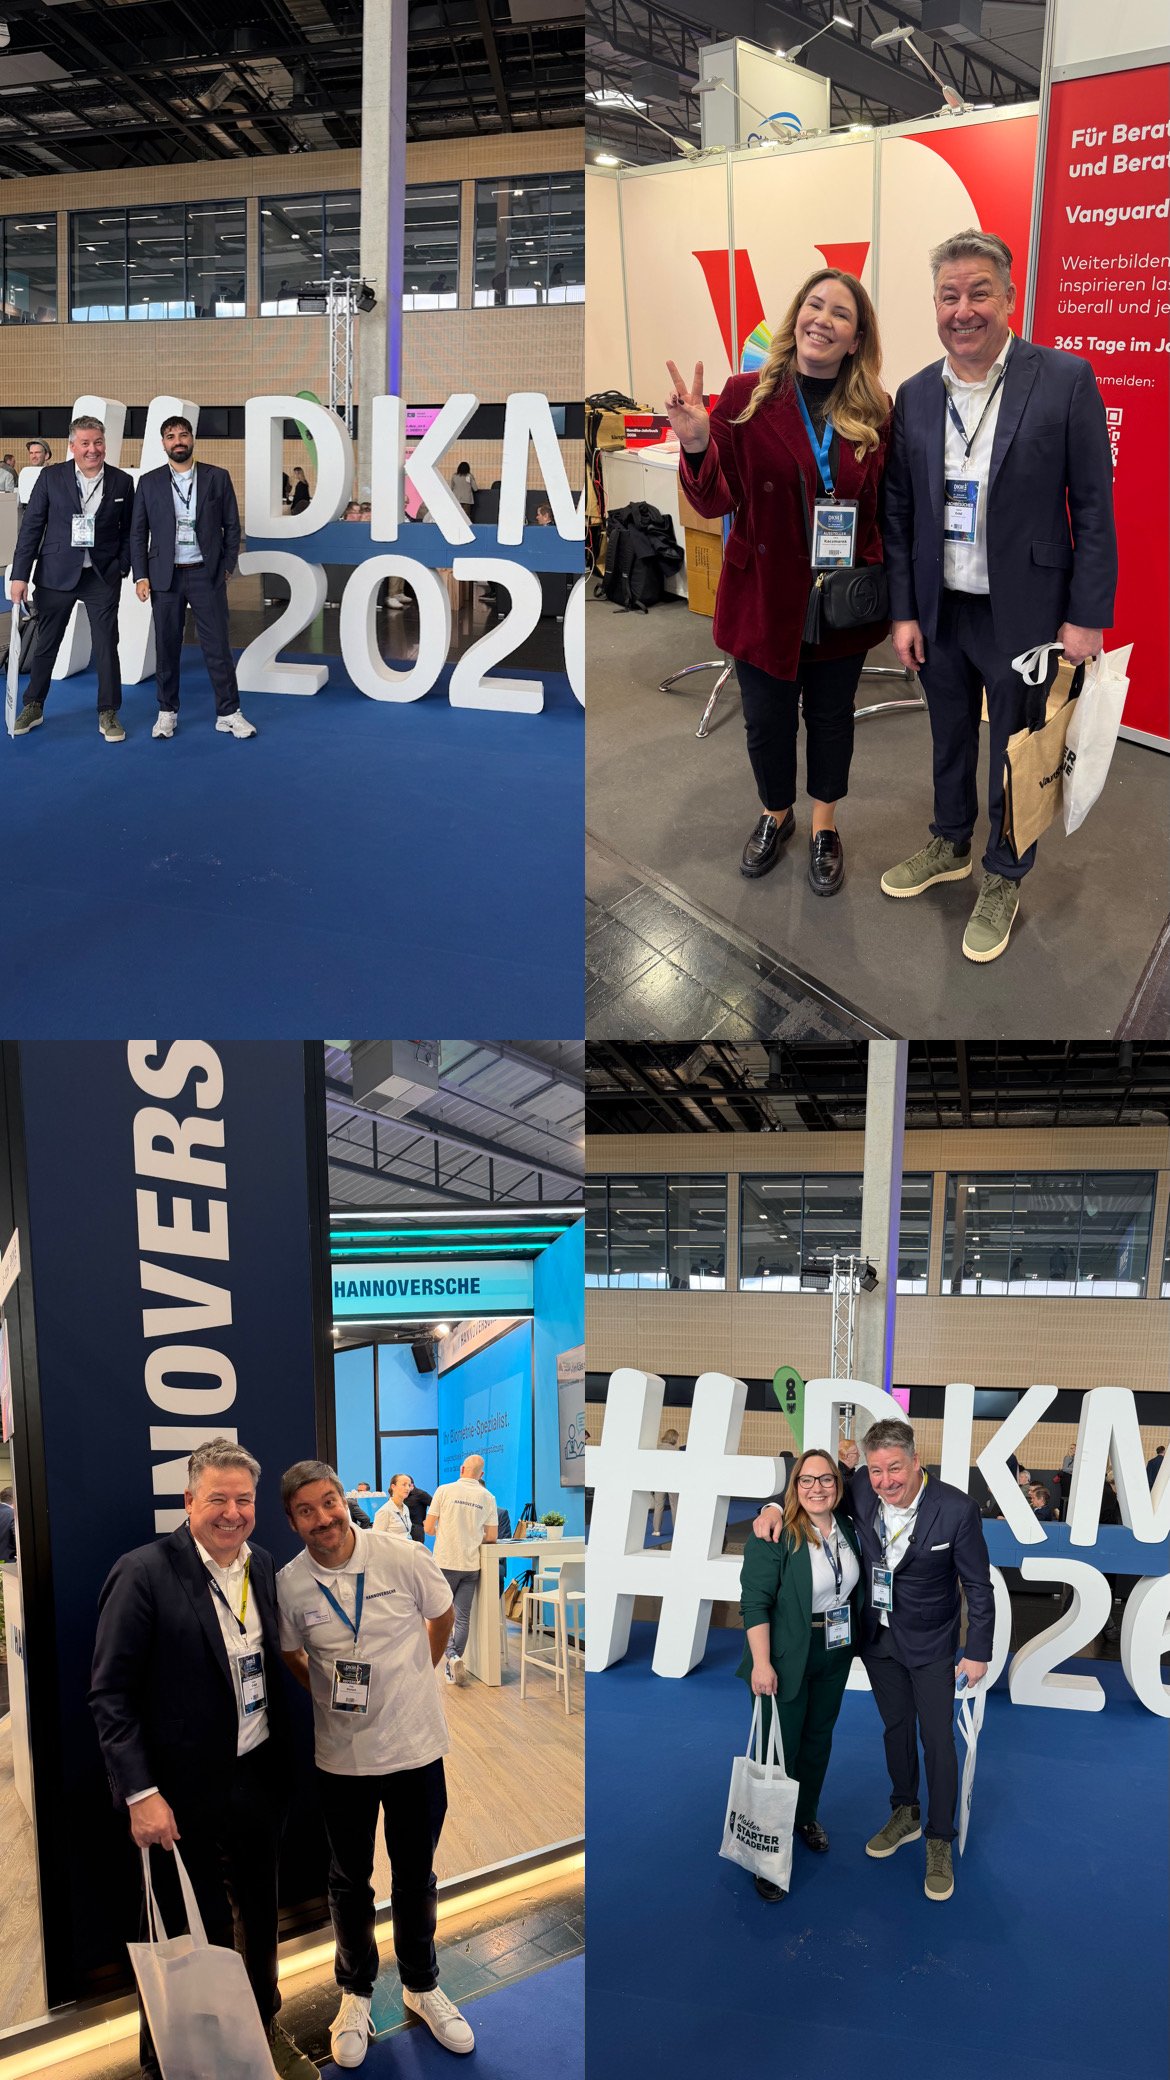
On 27 and 28 October 2026, NEOdirect visited DKM in Dortmund, the insurance industry’s trade fair. These visits help us ask providers about new products, revised conditions, service improvements, digital processes and solutions that may matter to international customers. They also give us a chance to discuss changes with existing partners.
Over the years, our team has built working relationships with contacts in different insurers, including specialist departments and key account managers. When a contract question is complicated or a service request has stalled, knowing where to direct the question can help us reach the right person. It does not guarantee a claim decision, faster settlement, or special legal treatment.
Our relationships with insurers are there to help our customers, not to make us loyal to one insurance brand.
Personal service starts when you need help
At NEOdirect, our work does not have to end when a policy is signed. A client can contact us with a landlord’s letter, an employment notice, an insurer’s response they do not understand, or a question about a possible legal-protection claim. They may want to know whether to ask for a coverage decision, what a deductible means, or which form to use.
We can review the insurance documents, explain the policy-related next step, help with communication with the insurer, and help the client find appropriate legal support when needed. We are insurance brokers, not a law firm. We cannot provide a legal opinion in place of a lawyer, and we cannot promise that an insurer will cover a specific dispute.
You can change your broker without automatically changing your policy
Many people already have insurance through CHECK24, another online platform, a different broker, or directly with an insurer. They may assume that getting a new adviser means cancelling their policy and buying another one. That is not necessarily the case.
In many situations, a customer can ask for an existing contract to remain in place while appointing a different broker for ongoing support. You do not need to buy new insurance just to get a better insurance broker. A broker appointment is separate from changing the insurer, cancelling the policy or changing its benefits.
There are practical conditions. The insurer may require a signed broker appointment, specific forms or confirmation before it records the new adviser. Not every insurer accepts every transfer, and an existing intermediary may have to be released or removed from the record. Until the insurer confirms the change, keep using the contact details already on your policy. NEOdirect can check the requirements for the specific company and contract before promising that it can take over the servicing.
This is useful for international residents in Germany who may not know that an insurance broker change can be separate from an insurance change. The policyholder stays in control: a transfer of broker is not permission to alter the contract.
Review first. Change only when it makes sense.
A careful review can look at the insured risks, benefits, deductible, exclusions, waiting periods, policy wording and the conditions that apply to the contract you already have. We can also check whether the same insurer offers another tariff or arrangement that may fit better.
Online platforms do not always show identical tariff versions or distribution arrangements. That does not mean an online policy is automatically worse. It means the actual policy documents matter. Where appropriate, we can ask the original insurer whether a different tariff or comparable condition is available, so the client may be able to stay with the same company.
There is no guaranteed saving and no automatic benefit to changing tariffs. A new tariff may have different cover, exclusions, waiting periods or conditions. We take account of existing protection and rights before discussing a change. Nothing should be altered without the customer’s agreement.
Sometimes the review confirms that the existing product is already a good fit. In that case, we will say so. Keeping a sound policy can be the right recommendation.
A practical way to manage policies: the simplr app
NEOdirect clients can use the simplr app to keep policy information and documents together. It can make everyday administration easier, but the app and a broker appointment are separate processes. Adding a contract to an app does not, by itself, transfer the broker relationship or change the insurer’s records.
-
Add your existing insurance
After becoming a client and receiving app access, add your existing policy information and documents in simplr.
-
We review your policies
We check which contracts we may be able to service and whether a review of benefits or conditions is worthwhile.
-
Choose what happens next
You decide whether to keep things as they are, request a broker transfer, or consider a change after its trade-offs are explained.
-
Get personal support
For questions about your insurance or a possible claim, contact your NEOdirect adviser for help with the insurance process.
Independent advice, with clear limits
NEOdirect is an insurance broker operating under the German licensing framework in Section 34d of the Trade Regulation Act (GewO). A broker is not simply the sales representative of one insurer. Our advice considers the customer’s needs and the relevant market access available to us, and any limits to that selection need to be clear.
Broker remuneration commonly includes commission paid by insurers when a policy is arranged or serviced. The arrangement can vary by product and service. We do not describe ourselves as universally commission-free, and any separate fee-bearing service should be explained before it is agreed.
Our purpose is not to sell another policy just because we can. It is to help people make informed insurance decisions, including the decision to leave a suitable contract unchanged.
Frequently asked questions
Can I change my insurance broker in Germany without changing my insurance?
Often, yes. A broker appointment can be separate from changing or cancelling a policy, but the insurer’s process and acceptance must be checked for your contract.
Can NEOdirect take over insurance purchased through CHECK24?
Possibly. It depends on the insurer, the contract and how the existing intermediary is recorded. NEOdirect can check the requirements; a transfer is not automatic.
Will my insurance premium increase if I change my broker?
A broker change alone does not normally rewrite the premium or benefits. The insurer may still change premiums under the contract, and any tariff change is a separate decision.
Can I get better conditions from my existing insurance company?
Sometimes. We can ask whether another tariff or arrangement is available, but availability, price and suitability are not guaranteed.
Can NEOdirect review my existing legal insurance?
Yes. We can review the documents, benefits, deductible, exclusions and waiting periods, then explain whether keeping the contract or considering another option appears more suitable.
Do I need to buy a new insurance policy to become a NEOdirect customer?
No. A new policy is not automatically required. Whether NEOdirect can service an existing contract depends on the insurer’s transfer process and confirmation.
What happens if I have a legal insurance claim?
Contact your insurer and NEOdirect before taking steps that may affect cover. We can help with the insurance process, but the insurer decides whether the policy covers the matter and a lawyer provides legal advice.
Can I contact NEOdirect on WhatsApp?
Yes. You can message the team on WhatsApp. Published office hours are Monday to Friday, 9:00 to 18:00; a response outside those hours is not promised.
Is NEOdirect an independent insurance broker?
NEOdirect operates as an insurance broker under Section 34d GewO. The relevant market selection and any limits should be explained as part of the advice.
How do I add my existing insurance policies to the simplr app?
After your NEOdirect account is set up, sign in to simplr, open Insurance and add the policy details. App entry does not itself transfer the broker appointment.