


Dental Insurance Guide for Indian Expats: How to Protect Yourself from Expensive Treatments in Germany
Why Dental Insurance Matters for Indian Expats in Germany
Many Indian expats experience their first real “cost shock” at the dentist after moving to Germany. This often happens when a crown, implant, or larger filling becomes necessary. While routine dental treatments are usually covered by statutory health insurance, more advanced procedures can quickly lead to out-of-pocket costs in the thousands of euros.
In India, private dental treatments are often significantly cheaper. However, traveling back for treatment is time-consuming, logistically difficult, and not always medically advisable. This is where dental supplementary insurance becomes important: it helps cover the gap between what your health insurance pays and the actual cost of modern dental care.
For many well-paid professionals working in Germany—such as IT specialists, engineers, researchers, or pharmaceutical professionals—this is not just a comfort issue. It is also about financial planning and avoiding unexpected expenses that can disrupt the family budget.
Dental insurance plans in Germany vary widely in terms of benefits and costs. Some plans reimburse up to 100% of the costs for high-quality dental prosthetics, while others only cover basic treatments. Many policies also include waiting periods and reimbursement limits during the first years of coverage.
Indian expats often face an additional challenge: many arrive in Germany as adults with an existing dental history that may include fillings, crowns, bridges, or previous root canal treatments. Not every insurance plan is designed to accommodate this situation, and some may exclude treatments that are already planned.
For this reason, it is important to choose a dental insurance solution that fits your personal situation, your dental history, and your long-term plans in Germany.
Statutory Insurance, Private Insurance and Dental Coverage: How Reimbursement Works
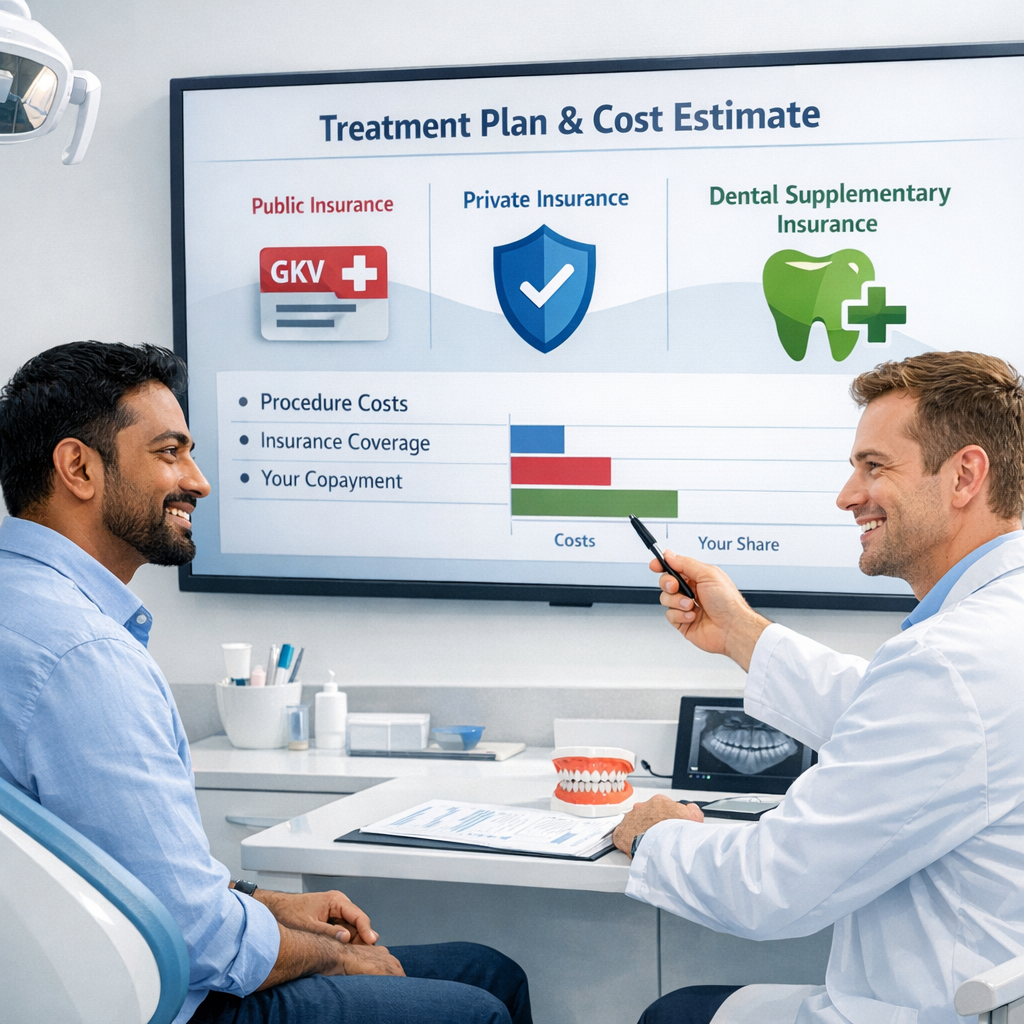
In Germany, statutory health insurance usually pays only a fixed subsidy for dental prosthetics. This subsidy typically covers around 40–60% of a basic standard treatment.
If you prefer higher-quality options—such as ceramic crowns, implants, or premium inlays—the additional costs must usually be paid by the patient.
Private health insurance plans can offer significantly better coverage, but they also operate with reimbursement percentages, limits, and waiting periods. Without additional dental coverage, patients may still face considerable out-of-pocket costs.
Dental supplementary insurance is designed to reduce these gaps. Depending on the plan, it can cover a large share of the remaining costs for:
- Dental prosthetics (implants, crowns, bridges)
- Dental treatments (fillings, root canal treatments)
- Preventive care (professional teeth cleaning)
- Orthodontics for children
For Indian expats, there are several aspects worth considering:
- Existing fillings, crowns, or bridges may affect future coverage.
- Patients with statutory health insurance benefit from maintaining a complete dental bonus booklet (“Bonusheft”), which increases the subsidy for prosthetics.
- Families with children often prioritize orthodontics and preventive treatments.
A sensible approach is therefore not simply choosing the most expensive insurance plan, but identifying which benefits are truly important for your situation. For example:
- Coverage for implants or high-quality crowns
- Regular preventive care such as professional cleanings
- Orthodontic coverage for children
- Short waiting periods and realistic reimbursement limits
Once these priorities are clear, it becomes much easier to select a plan that offers predictable costs and minimizes future financial surprises.
How Indian Expats Can Find the Right Dental Insurance in Germany
After understanding how the German system works, the next step is choosing a dental insurance plan that genuinely fits your personal situation.
A structured approach usually includes three steps.
1. Understanding Your Current Situation
- Are you insured under statutory or private health insurance?
- Do you already have fillings, crowns, or bridges?
- Are you planning to stay long-term in Germany?
- Do you have children or plan to start a family?
- What monthly premium fits comfortably within your budget?
2. Comparing Dental Insurance Plans
Once the personal situation is clear, different insurance plans can be compared based on key factors such as:
- Reimbursement rates for dental prosthetics
- Coverage for dental treatments
- Preventive care benefits
- Orthodontic coverage for children
- Waiting periods and reimbursement limits in the first years
3. Long-Term Planning
A well-chosen dental insurance plan helps ensure that future dental decisions are based on medical needs rather than financial concerns. Instead of worrying about unexpected bills, patients can focus on receiving the treatment that best protects their long-term dental health.
For many Indian expats living in Germany, dental supplementary insurance is therefore not a luxury—it is a practical way to manage healthcare costs and maintain access to high-quality dental treatment.
With the right plan in place, dental care in Germany becomes far more predictable, transparent, and financially manageable.
Erfahren Sie mehr über private Krankenversicherung (PKV) in Deutschland und wie Neodirect Ihnen helfen kann, den richtigen Schutz zu finden.
Jetzt handeln: Kostenloses Beratungsgespräch buchen – ein Neodirect-Berater hilft Ihnen auf Englisch, die beste Versicherungslösung für Ihr Leben in Deutschland zu finden.